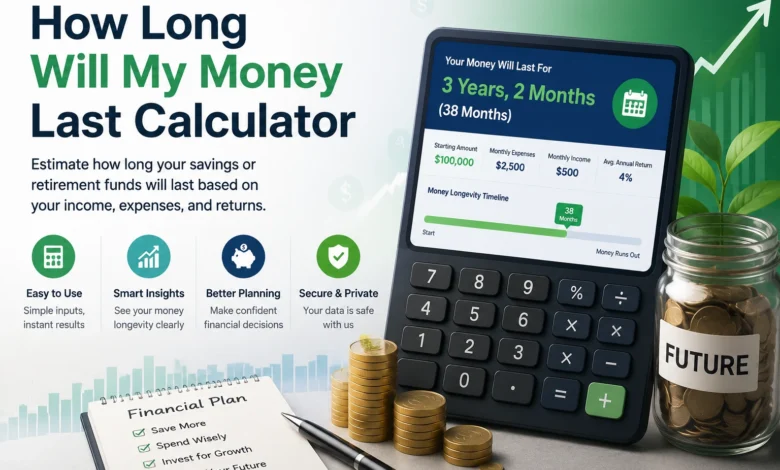
Managing your money becomes easier when you understand how long your savings can support your lifestyle. A how long will my money last calculator is a useful financial tool that helps estimate how many months or years your available funds may last based on your savings, expenses, income, and other financial factors.
Many people use this type of calculator when planning retirement, managing emergency savings, preparing for career changes, or reviewing their overall financial position. The length of time your money lasts depends on several factors, including monthly spending, income sources, inflation, investment growth, and unexpected expenses.
In this guide, you will learn how the how long will my money last calculator works, how to estimate your savings duration, what factors affect your results, and how you can better understand your financial timeline.
What Is a How Long Will My Money Last Calculator?
A how long will my money last calculator is an online financial planning tool that estimates how long your savings or available funds may continue based on your financial information. It helps users understand their financial runway by comparing their current money with their expected expenses and income.
This calculator is especially useful for people who want to know how long their savings will last without income, how much they can safely withdraw, or whether their current funds may support future goals. However, the result is only an estimate because real-life financial situations can change.
A calculator cannot predict every future event, such as unexpected medical costs, changes in income, market conditions, or lifestyle changes. Instead, it provides a helpful starting point for understanding your money situation and making informed financial decisions.
How Does a Money Last Calculator Work?
A money longevity calculator works by analyzing the relationship between your available savings and your financial needs. It uses information you provide to estimate how quickly your money may decrease or how long it could continue supporting your expenses.
The main information typically required includes your current savings balance, monthly expenses, monthly income, expected withdrawals, investment returns, and inflation assumptions. Each factor plays an important role in determining the final estimate.
For example, having a larger savings balance generally increases how long your money lasts, while higher monthly expenses can reduce your financial timeline. Additional income sources or investment growth may extend the duration of your savings. Learning about successful financial companies and investment approaches can also help readers understand how money management strategies work in real-world situations.
Important inputs usually include:
- Current savings balance: The amount of money you currently have available.
- Monthly expenses: Your regular costs, including housing, food, transportation, and bills.
- Monthly income: Money coming in from work, benefits, or other sources.
- Withdrawals: The amount you plan to take from savings regularly.
- Investment returns: Possible growth from invested funds.
- Inflation rate: The expected increase in the cost of goods and services over time.
How to Calculate How Long Your Money Will Last
The simplest way to estimate savings duration is by using a basic formula:
Starting Savings ÷ Monthly Expenses = Number of Months Money Can Last
For example, if you have $20,000 in savings and your monthly expenses are $2,000, you can estimate:
$20,000 ÷ $2,000 = 10 months
This basic calculation assumes there is no income, inflation, investment growth, or unexpected spending. It provides a quick estimate but does not represent a complete financial forecast.
More advanced calculations include additional factors such as investment returns, taxes, inflation, and changing expenses. A savings duration calculator may consider these details to create a more realistic estimate.
For example, someone with $100,000 in savings and monthly expenses of $3,000 may have a different result depending on whether they earn income, invest their money, or experience rising expenses.
Factors That Affect How Long Your Money Lasts
Many financial factors can influence how long your savings can support you. Understanding these factors can help you create more realistic expectations when using a how long will my money last calculator.
Spending habits are one of the biggest influences. A person with lower monthly expenses may be able to stretch savings much longer than someone with expensive lifestyle choices. Small changes in daily spending can significantly affect long-term savings duration.
Monthly bills also play an important role. Housing payments, insurance costs, transportation expenses, and debt payments can quickly reduce available savings. Reducing unnecessary costs may help extend your financial runway.
Other important factors include:
- Emergency expenses: Unexpected repairs, health costs, or family needs can reduce savings faster.
- Debt payments: High-interest debt can significantly shorten how long money lasts.
- Inflation: Rising prices reduce the purchasing power of saved money.
- Investment performance: Positive returns may increase savings, while losses may reduce them.
Because these factors can change over time, it is important to review your calculations regularly.
How Long Will Different Amounts of Money Last?
The answer to questions like how long will $50,000 last or how long will $100,000 last depends on spending habits, income, location, and financial goals. There is no single answer because every person has different expenses and financial circumstances.
For a simple example, the table below shows estimated durations based only on savings divided by monthly expenses. These examples do not include income, inflation, taxes, or investment growth.
| Savings Amount | Monthly Expenses | Estimated Duration |
| $10,000 | $2,000 | About 5 months |
| $50,000 | $2,500 | About 20 months |
| $100,000 | $3,000 | About 33 months |
These estimates are only examples. Someone with additional income may make their money last much longer, while someone facing high expenses may use savings more quickly.
A personal finance calculator can provide a more accurate estimate when you include your own financial details, such as income sources, expected withdrawals, and investment information.
How Long Will My Money Last in Retirement?
Retirement planning often requires a more detailed approach because savings may need to support a person for many years. People commonly use retirement savings calculators to estimate whether their funds may last throughout retirement.
When calculating retirement savings duration, several factors matter. These include retirement withdrawals, Social Security income, pension payments, investment returns, taxes, and healthcare expenses.
Retirees may withdraw money regularly from savings accounts, retirement accounts, or investments. A retirement calculation helps estimate how those withdrawals may affect future savings.
Healthcare costs are another important consideration because medical expenses can increase over time. Since retirement may last decades, using a calculator with realistic assumptions can help people better understand their financial position.
How Inflation Impacts How Long Your Savings Will Last
Inflation means the cost of goods and services increases over time. As prices rise, the same amount of money may buy fewer products and services in the future.
For example, if your monthly expenses increase because of higher housing, food, or healthcare costs, your savings may disappear faster than expected. This is why many calculators include an inflation rate when estimating future savings duration.
Ignoring inflation can create an unrealistic picture of your financial future. A savings withdrawal calculator that considers inflation may provide a more practical estimate because it accounts for changing costs over time.
How to Make Your Money Last Longer
There are several general strategies that may help improve financial stability and extend savings duration. The right approach depends on each person’s goals, situation, and financial priorities.
Reducing unnecessary expenses is one common way to protect savings. Creating a monthly budget can help identify spending patterns and areas where costs may be reduced.
Other helpful strategies include:
- Building emergency savings for unexpected expenses.
- Increasing income through additional work or other opportunities.
- Avoiding high-interest debt whenever possible.
- Reviewing subscriptions and regular expenses.
- Investing according to personal financial goals and risk tolerance.
Careful money management does not guarantee a specific outcome, but it can help create better financial awareness and planning habits.
Common Mistakes When Estimating How Long Money Will Last
Many people make mistakes when trying to estimate their savings duration. One common mistake is ignoring inflation and assuming today’s expenses will remain the same forever.
Another mistake is underestimating monthly expenses. Similar financial mistakes can also happen when making major money decisions, such as business purchases or investments. Some people calculate only major bills but forget smaller costs such as maintenance, transportation, subscriptions, and unexpected purchases.
Other common errors include:
- Forgetting emergency expenses.
- Assuming investment returns are guaranteed.
- Not including taxes or fees.
- Failing to update calculations as financial situations change.
Regularly reviewing your numbers can help create more realistic estimates and improve your overall financial planning.
Benefits of Using a Savings Duration Calculator
A savings duration calculator can provide several benefits for people who want a clearer understanding of their finances. It helps organize financial information and shows how different choices may affect future savings.
One major benefit is better financial planning. By understanding how long money may last, users can make more informed decisions about spending, saving, and income goals.
Other benefits include:
- Understanding spending limits.
- Preparing for retirement.
- Evaluating emergency savings.
- Comparing different financial scenarios.
- Improving money management habits.
A calculator does not replace professional financial guidance, but it can be a useful educational tool for understanding personal finances.
What Information Do You Need Before Using the Calculator?
Before using a how long will my money last calculator, gathering accurate financial information can improve the quality of the estimate. Having realistic numbers helps create a more useful result.
You should prepare details such as:
- Current savings amount.
- Monthly expenses.
- Monthly income.
- Expected withdrawals.
- Investment information.
- Inflation assumptions.
The more accurate your inputs are, the more meaningful the calculation may become. Reviewing your information regularly is also important because expenses, income, and financial goals can change.
Conclusion
A how long will my money last calculator is a helpful tool for estimating how long your savings may support your financial needs. By considering savings, expenses, income, inflation, and investments, it provides a clearer picture of your financial timeline.
The results should be viewed as estimates rather than guarantees because financial situations can change. Regularly tracking expenses, reviewing savings goals, and updating calculations can help you make better-informed money decisions.
Whether you are planning retirement, building emergency savings, or managing current finances, understanding your savings duration is an important part of responsible financial planning.